Blog
Canada vs U.S. payroll: what changes for a U.S. employer
The differences a U.S. company meets when it pays employees in Canada: provincial instead of state tax, CPP and EI instead of Social Security and Medicare, TD1 and T4 instead of W-4 and W-2, and stricter remittance deadlines.
Published November 20, 2025 · Updated October 21, 2026
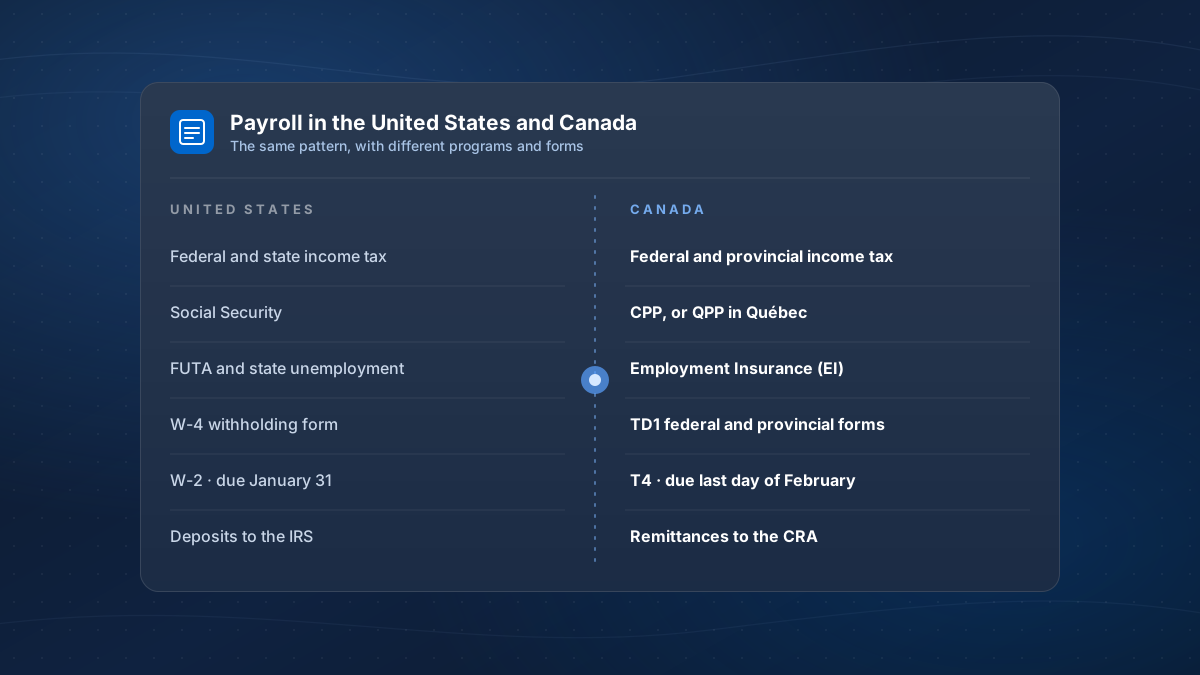
Canadian payroll follows the same broad pattern as U.S. payroll: withhold income tax and social contributions from each pay, add the employer’s share, remit it to the tax authority, and report the year on a slip. The details differ at almost every step, and the differences are where U.S. employers get caught. This article compares the two systems; for how Canadian payroll runs step by step, see our Canadian payroll guide.
The deductions side by side
| United States | Canada | |
|---|---|---|
| Income tax | Federal, plus state (and sometimes local) | Federal, plus provincial (Québec collects its own) |
| Retirement program | Social Security | Canada Pension Plan (CPP), or Québec Pension Plan (QPP) in Québec |
| Health program | Medicare | Public health care, funded through taxes; some provinces charge employers a payroll health tax |
| Unemployment | FUTA and state unemployment (employer-paid) | Employment Insurance (EI), paid by employer and employee |
| Parental benefits | Varies by state | Through EI; Québec runs its own plan (QPIP) |
| Workplace injury | State workers’ compensation | Provincial workers’ compensation board |
Two practical differences stand out. First, Canadian contribution rates and maximums change every January, and CPP now has a second tier of contributions on earnings above the first ceiling. Use the CRA’s current CPP and EI pages rather than last year’s figures. Second, the employer’s EI share is higher than the employee’s, unlike Social Security and Medicare, where the two shares match.
Forms
| Purpose | United States | Canada |
|---|---|---|
| Employee’s withholding information | W-4 (and state form) | TD1 federal and provincial forms (TP-1015.3-V in Québec) |
| Annual employee slip | W-2 | T4 (plus RL-1 in Québec) |
| Annual slip for non-employees | 1099-NEC | T4A, where it applies |
| Slip deadline | January 31 | Last day of February |
| Record of a job ending | No federal equivalent | Record of Employment (ROE), issued to Service Canada |
The Record of Employment surprises most U.S. employers: whenever an employee has an interruption of earnings (they leave, are laid off, or go on leave), the employer must issue an ROE so the employee can claim EI. We compare the slips in more detail in W-2 and 1099 vs the Canadian T4.
Remittances
U.S. employers deposit federal employment taxes on a monthly or semi-weekly schedule set by the IRS lookback rules. In Canada, the CRA assigns a remitting frequency based on the employer’s average monthly withholding: most new employers remit monthly, small employers may qualify for quarterly remitting, and larger employers remit more often. Late remittances carry penalties that start at 3% and rise to 10% of the amount due, plus interest, and the CRA can hold company directors personally liable for unremitted source deductions. Québec employers remit provincial deductions to Revenu Québec separately.
Records
The CRA expects payroll records to be kept for six years from the end of the last tax year they relate to. The IRS asks for employment tax records to be kept for at least four years. Provincial employment standards add their own requirements for hours, wages and vacation records.
Where U.S. employers go wrong
- Applying the wrong province. Tax and employment standards follow the province where the employee works, not your head office.
- Using last year’s rates. CPP, EI and tax brackets change each January.
- Treating vacation as a policy choice. Vacation time and vacation pay are statutory minimums in every province.
- Missing the ROE. It is required whenever earnings stop, not only at termination.
- Running Canadian payroll from U.S. software without Canadian tax tables, TD1 handling and T4 or RL-1 filing.
The Employer of Record alternative
If you would rather not register as a Canadian employer at all, an Employer of Record runs Canadian payroll as the legal employer: deductions, remittances, slips, ROEs and records. You approve the hire and direct the work, and receive one monthly invoice. See how our Employer of Record service works.
Next steps for hiring in Canada
-
How it works
The steps from your chosen candidate to their first payroll, and who does what.
-
Employer of Record
How InfraDev employs your hire in Canada so you don’t need a Canadian entity.
-
Compare your options
EOR, your own Canadian entity, or contractors: cost, timeline and risk.
-
Hiring in Canada guide
Payroll, CRA registration and employment law for U.S. companies.
Planning a hire in Canada?
Tell us the role and province. We'll explain how employment, payroll and compliance would work for your team.