Blog
W-2 and 1099 vs the Canadian T4 and T4A: what U.S. companies should know
How the Canadian T4 and T4A compare with the U.S. W-2 and 1099-NEC: what each slip reports, when it is due, what it says about the employment relationship, and why a 1099-style contractor in Canada is often an employee.
Published November 20, 2025 · Updated October 21, 2026
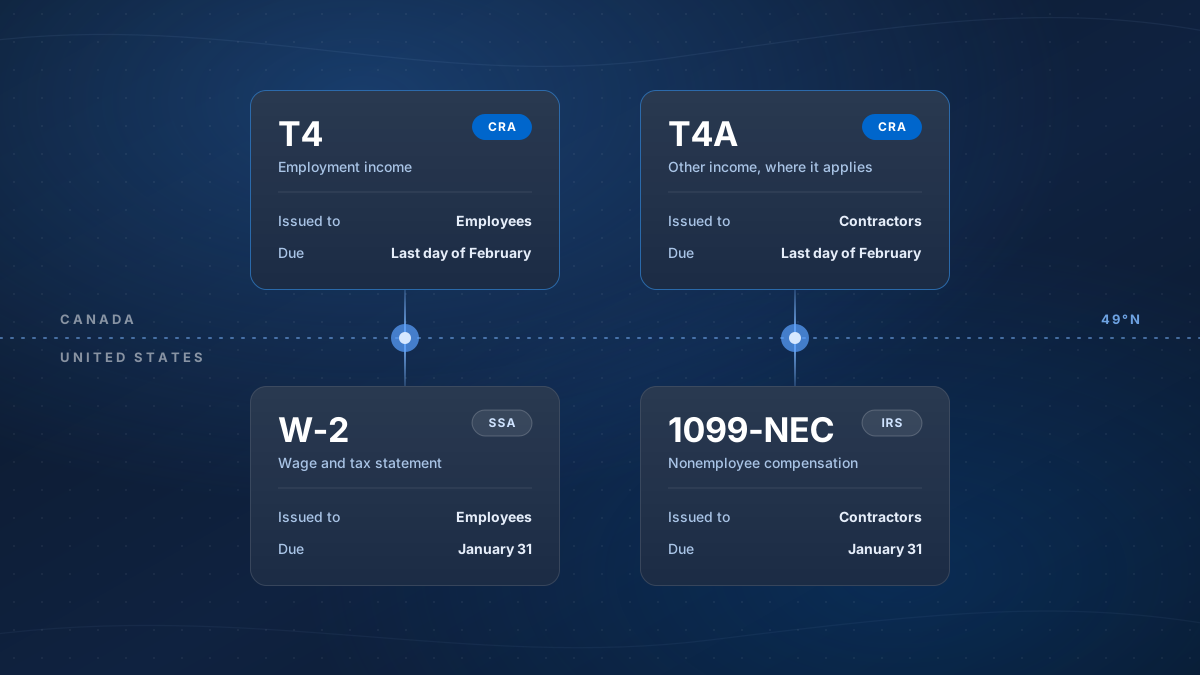
A U.S. company that hires in Canada swaps the W-2 for the T4 and, for contractors, the 1099-NEC for (sometimes) the T4A. The forms look alike, but the relationship behind them is decided differently, and that is where the risk lies. This article compares the slips and explains the classification question behind them.
The four slips at a glance
| W-2 | 1099-NEC | T4 | T4A | |
|---|---|---|---|---|
| Country | United States | United States | Canada | Canada |
| Issued to | Employees | Independent contractors | Employees | Contractors and other payees, where it applies |
| Tax withheld | Yes | Generally no | Yes | Generally no |
| Social contributions | Social Security and Medicare, employee and employer shares | Contractor pays self-employment tax | CPP or QPP and EI, employee and employer shares | Contractor pays both CPP shares on self-employment income; no EI |
| Due | January 31 | January 31 | Last day of February | Last day of February |
| Filed with | Social Security Administration | IRS | CRA | CRA |
In Québec, employers also issue an RL-1 slip for each employee, filed with Revenu Québec by the same February deadline.
What the T4 reports
The T4 is the Canadian counterpart of the W-2. The boxes a U.S. finance team will look at first:
- Box 14: employment income
- Box 16: employee’s CPP contributions (Box 16A: second-tier CPP2 contributions)
- Box 17: employee’s QPP contributions (Québec)
- Box 18: employee’s EI premiums
- Box 22: income tax deducted
- Box 24: EI insurable earnings
- Box 26: CPP/QPP pensionable earnings
Unlike the W-2, the T4 shows no state-style split: federal and provincial income tax are withheld together and reported as one figure (Québec provincial tax goes on the RL-1). The CRA’s page on filling out T4 slips lists every box.
What the T4A covers
The T4A reports several kinds of income, including fees for services paid to self-employed individuals in some situations. Whether a payer has to issue one depends on the payer and the payment, so check the CRA’s T4A slip page. A U.S. company paying a Canadian contractor does not issue a 1099-NEC to them; the contractor is a foreign person for U.S. purposes and typically provides a W-8BEN.
Contribution rates
Social Security and Medicare rates are set in law and rarely change; the Social Security wage base changes each year. Canada’s CPP and EI rates and maximums are reset every January, and CPP now has a second tier on earnings above the first ceiling. Take current figures from the CRA’s CPP and EI pages. Note that the employer’s EI premium is 1.4 times the employee’s, while U.S. FICA shares are equal.
The classification question
The slip follows the relationship, not the other way around. Both countries look at the substance of the work:
- United States: the IRS groups the evidence into behavioural control, financial control and the type of relationship (IRS guidance).
- Canada: the CRA and the courts ask whether the person is in business on their own account, weighing control, ownership of tools, chance of profit and risk of loss, and integration into the payer’s business (CRA guidance).
In practice, a full-time Canadian “contractor” who works only for you, on your schedule, with your tools, under your managers is likely an employee in Canada, whatever the contract says. If the CRA reclassifies the relationship, the payer can owe the CPP and EI that should have been deducted, plus penalties and interest, and the worker may have employment standards claims. See EOR vs contractor for the full comparison.
What this means for a U.S. company
- Employees in Canada need Canadian payroll: TD1 forms, source deductions, remittances, T4 slips (and RL-1 in Québec), and Records of Employment. An Employer of Record can do all of this as the legal employer.
- Genuine contractors invoice you, charge GST/HST where required, and report their own income. Our consulting management service holds the contract and handles invoicing and tax forms.
- When in doubt, treat a long-term, directed role as employment.
Our Canada vs U.S. payroll article compares the rest of the payroll cycle.
Next steps for hiring in Canada
-
How it works
The steps from your chosen candidate to their first payroll, and who does what.
-
Employer of Record
How InfraDev employs your hire in Canada so you don’t need a Canadian entity.
-
Compare your options
EOR, your own Canadian entity, or contractors: cost, timeline and risk.
-
Hiring in Canada guide
Payroll, CRA registration and employment law for U.S. companies.
Planning a hire in Canada?
Tell us the role and province. We'll explain how employment, payroll and compliance would work for your team.